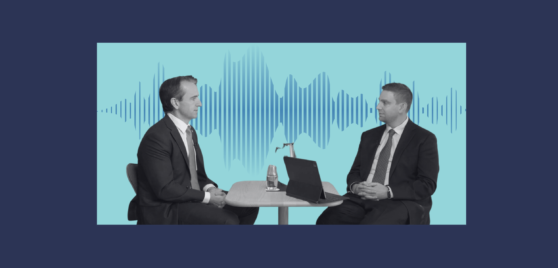
Featuring Josh Freiman and CBA CEO Matt Comyn
WATCH
READ
Managing a major financial institution has never been easy, but with the global and local economy changing ever more rapidly it’s harder than ever. Commonwealth Bank of Australia (CBA) has navigated this environment better than most and in recent years has reinforced its market-leading position, particularly in the crucial youth demographic.
In this first video podcast of our new series “The company we keep”, IML Equities Analyst Josh Freiman talks to CBA CEO, Matt Comyn about:
- Why he started his career with an aviation degree and unexpectedly transitioned into banking (44 seconds)
- Why he exit interviews for junior staff and what management meetings fail to reveal (01.47)
- How CBA is leveraging its dominant 43% main financial institution share among 18-to-24-year-olds (05:07)
- The real-time spending and saving trends CBA is observing across its 14 million daily digital customer logins (11:16)
- Why the current high interest rate environment is acting as a massive wealth transfer agent between generations (14:17)
- How CBA is approaching AI, where it is seeing productivity benefits and what AI might mean for the banking workforce over the next decade (16:32)
- The one thing Matt hopes the next leader of CBA won’t change (24:50)
‘The company we keep’ is a new IML series where we interview leaders from the companies within IML’s portfolios. The next edition will feature Grant Hacket OAM, champion swimmer and Chief Executive Officer of Generation Development Group
Lightly edited transcript – recorded on Wednesday 16 September. Transcript has been generated by AI so may not be completely accurate.
Josh: Welcome to The Company We Keep, conversations with the leaders of the companies we own. IML has been managing money on behalf of retail investors since 1998, and staying close to the boards and companies we own is a central part of the investment process. For the podcast today, we are lucky enough to be joined by Matt Comyn, the CEO of CBA, where we will be discussing a range of topics from the economy, the new tax changes, and the impact on housing, and finally, the impact of AI on CBA, the sector, and the workforce. Welcome to the podcast, Matt.
Matt: Great to be with you.
Josh: Great to have you. Maybe if I just start on a more personal note, one of the things I found quite interesting when I was doing research for this podcast was that you actually had a non-traditional start to your banking career. I noticed you studied a Bachelor of Aviation at UNSW and I presume you were going to fly planes. What changed and what brought you into banking?
Matt: I did. I did a Bachelor of Aviation, then a Master’s in Commerce. I mean, it was a new course. I was not necessarily going to become a pilot. I was sort of interested in the field. I would have to say that I wouldn’t say I apply it regularly. But I think university teaches you a lot of things, and one of them is how to learn, how to think about problem-solving. My entry into CBA was actually quite fortuitous. I met one of the directors of CommSec, and we got chatting and I got an opportunity to join CBA and, I guess, never looked back.
Josh: I mentioned CommSec because my next question actually feeds in nicely. A colleague I still work with, Bruce Du, started his career as a graduate at CommSec, and when he left CommSec, you as CEO actually held his exit interview, which I found quite amazing and perhaps a little bit different to other CEOs that we’ve spoken to. So I just wanted to ask you, why did you choose to do exit interviews for junior staff, and what did you learn from them that you wouldn’t learn in a management meeting?
Matt: Firstly, as I said, when I started in CBA, I was in the equities division alongside CommSec. I was really lucky to work from the beginning around a group of people that were innovating inside the bank. The business was growing really rapidly then, you can imagine, in 1999 and 2000. I was lucky enough, after doing some other roles in between, to lead that business from 2006 to 2010.
I wouldn’t say I have always done every exit interview, but I generally think one of the important lessons in leadership is, certainly as you become more senior in any organisation, you have to accept that you are not always going to get the complete picture and you get a very filtered version of what is going on. I don’t mean that in terms of people deliberately trying to withhold information. I just think there is no substitute for firsthand observations. It is the same way you can learn things about how you can improve what you are doing for customers from speaking with customers.
I think often people are very open when they have made a decision to leave an organisation. Sometimes that could be for a great opportunity. Sometimes it can be that there is something that just didn’t work from a fit or a cultural perspective. So, yeah, I’m just a big believer that you have to keep learning and improving every day at an individual level. I think that is equally true of an organisation. Having lots of different mechanisms to try to make sure that you are getting the best overall picture is key, and it is the role of the leader to synthesise that, clarify it, and work out what things you want to work on. I have got lots of insights from people in probably unexpected and maybe less formal situations.
Josh: Is that something you still do today?
Matt: Yeah. I mean, again, you have got to do it in different ways and often maybe in slightly unpredictable ways. I am a big believer in being close to the work, and I think being close to the customer is crucial.
On a couple of customer visits today, I started the day in Canberra, but I have seen a couple of clients. I think there are lots of ways to interact. It is one of the reasons I like working in the office; you can glean a lot of things from what is going on around you. There are lots of things around organisational design, but absolutely, as CEO, you should be very reluctant to always believe the messages that you are being told. I just think that is human nature inside a large organisation. It tends to improve as it goes through a management hierarchy. So I think it is really important to be prepared to go directly to the information source versus relying on the filtered version.
Josh: Switching to a more CBA-focused question, one of the things at IML that we really do when we undertake due diligence on the companies that we seek to, and subsequently do, own is look for a sustainable economic moat or a competitive advantage. You guys have multiple, actually.
One may talk to your funding, but in today’s situation, I’m actually going to refer to your leadership market share in youth. When I look at your retail bank and I look at the MFI statistics, you actually hold approximately 43% to 44% of that 18-to-24-year-old category. But when I look at the mortgage environment, approximately 75% of mortgage customers are now going with a broker.
How do you, as CEO, engage the business to convert a high proportion of that leadership that you have in youth, and how do you measure it?
Matt: I think that is a really important question. Just as an investor does, inside any business, you are trying to make sure you understand what your sources of competitive advantage are and how durable they are. I remember we first put that slide—it is the Roy Morgan MFI slide—into our results. I am pretty sure it was 2014, when I was in the retail bank, because it is actually a very neat encapsulation of one of those advantages.
As you said, we start with a very high share. In banking, traditionally, there are two sources of new accounts: one is youth, and the other is migrants. We do very well in both of those. Then, of course, part of our job is to try and retain as many of those customers as we can, and there are lots of different ways we have tried to do that. Structurally, we are advantaged because we have done well on those. Obviously, Australia has been—until more recently when the birth rate has been declining and migration is now coming down—that has been a real driver.
I think it is a simple encapsulation. As you said, it underpins the business because, typically, when you get the main banking relationship, the customer tends to have their transaction account with you. This leads to a liability-led funding advantage, funding stability, better risk identification, lower cost to serve, and a deeper relationship.
Specifically, as you talk to the mortgage market, it has evolved a lot since the mid-90s with securitisation and mortgage brokers, with intermediaries providing choice and certainly the perception of price. That has been a big focus for us. We do well, certainly on a relative basis, through our proprietary channels. I think with any business, if you have the choice, you would prefer to deal directly with your customers, but mortgage brokers have grown tremendously and are an important distribution channel. To the essence of your question, there are some important elements of what we would consider to be our competitive advantage, and we should be spending a lot of time thinking about how we retain that, how we earn that right every day, what the sources of durability are, and how they could be challenged over time.
Josh: Topically, in the current environment, there is obviously a lot of news on the housing market. House prices are falling, and application volumes are down. I’m conscious that you guys reported that application volumes had fallen sort of 15% since May at your recent results, but then stabilised into August. I just wanted to check, has there been any change in how that is tracking? And do you have any commentary on how it is differing between different mortgage product types and customer segments?
Matt: Josh, you probably won’t be hugely surprised that I won’t update with the latest information. But look, you are right. We anticipated that with the full-year results there would be a lot of focus on housing. That said, it was a very significant focus, guess, even more so in the media than with investors. That sounds like a silly thing, but I’m glad we put the line graph in versus just spot numbers in terms of changes to applications.
If you go back, obviously, last calendar year was a very strong year for credit growth, housing credit growth, house prices, and application volumes. They peaked in October, and then you get a combination of expectations around rates, affordability, rate rises coming into the start of the calendar year, and, as you mentioned, tax changes, which have had a lot of focus in the lead-up to the budget and since then. What we did see is a continuation of the reduction.
As you touched on, investor volumes, as you would expect, have softened because of tax changes and changes to the returns. You would expect investors to reassess the attractiveness of housing. These are policies that are designed to shift some of the investor characteristics of housing, but those transitions are hard as well.
I think the best thing I would say is a repeat of what we said at the full-year, which was, yes, you can see the reduction, and we saw that trough in sort of late June, early July, and then a stabilisation. If you look very closely, which I’m sure you have at the line graph, there is a slight tick up. But on a year-on-year basis, applications have softened and house prices started falling in about March. Given how much of household assets and wealth are held in housing, of course, it is something that is watched very closely.
As you and lots of younger Australians would appreciate, being able to participate in owning a house is also important. Worryingly, that has been feeling more out of reach than when I started working. Trying to get that balance right is really important.
Josh: When market analysts typically look at statistical aggregates or market releases from the ABS, they get a picture, but it is perhaps a little bit backward-looking. CBA is the largest retail bank in Australia. One in three Australians are retail bank customers. You have 14 million logins a day. You guys should have the best real-time data picture on customers’ behaviour, pressures, stress, and spending. I just wanted to check, what has changed in how people are spending their money and saving their money over recent history?
Matt: To your point, I think the real-time nature is very helpful. It is particularly useful when there are shocks happening within the economy. Just as there was so much focus on the housing graph and exactly how much the line had moved, I can remember being in periods during both the onset of COVID and then when there were big changes in interest rates where you quickly see changes to consumption. We put out some of those charts in the results in terms of spending behaviour.
The key message is that people feel the effects. Inflation tends to affect everyone, and particularly lower-income households. Monetary policy, given the distribution of both savings and debt, can clearly have a bigger impact. That explains some of the sentiment and the differences that you can feel between people who have benefited from higher rates—when they are perhaps at the end of repaying a mortgage and have some savings—versus those who have just bought their first home or are still holding pretty high levels of household debt relative to their income. You feel that quite sharply.
Then you see some interesting movements in discretionary expenditure. I think that has actually held up. Spending overall has held up pretty well. I think what is interesting at the moment is there is quite a deviation between what the sentiment is more broadly—what people are feeling—versus the revealed expenditure, which has been relatively stable across most categories.
Clearly, this combination of global factors—greater uncertainty, the oil price shock earlier in the year, and rates going up—is weighing on people. At the moment, there is an expectation of another rate hike, and I think that is weighing on people a lot. That sentiment is being felt quite sharply, and that is obviously leading to some differences in the way people are expressing that politically, which influences some of the policies. Sometimes it is about understanding the micro, but it is also important to understand the macro thematically and what that is going to lead to.
Josh: Just touching on your answer a little bit, I’m conscious that the media is always obsessed with how much people are paying to CBA and other banks in the form of their mortgage expense and mortgage interest. But I think I’d be remiss not to mention that you guys paid depositors and savers $22.7 billion last year.
However, I’m conscious that the distribution of who has a mortgage is primarily focused on 25-to-44-year-olds, and who has those deposits is primarily focused on the over-65 category. So, in a higher-rate environment, it is not just a handbrake on economic activity, but it also operates as a wealth transfer agent that causes wealth disparity. Are you seeing that play out in customer spending and saving habits?
Matt: Yeah, we are. As you said, there is quite a big shift. Rates were effectively coming down for many years, and we have been well below the current levels. But then obviously, if you go back multiple decades, rates had been much higher. You see this trajectory of rates continuing to fall, and then a very sharp reversal from 10 basis points to 4.35%, which also saw house prices fall by just over 8%. That was a very big shift.
For many people, that was probably further and faster than they expected rates to go, and obviously introductory inflationary forces really took effect on a global basis. But if you take a long-run view, rates aren’t actually that high relative to where they have been, though clearly there are high expectations both domestically and on a global basis. We are seeing that play out in the US now with more inflationary forces.
Adjusting to that is taking some time. That has shifted, and it is felt sharply in Australia because we have both a very high proportion of variable-rate mortgages, as well as relatively high household debt. There is a lot of interest in movements in the cash rate here, and no doubt there is a lot of media focus because people are very interested in it as it affects them directly and quickly.
Josh: Touching on AI, I’m conscious that at a CBA forum, I think it was in May, Sam Altman was speaking, and you asked him the question: where are the productivity benefits in AI? He said if we are still asking that question in 12 months, he’d be very worried. We are sort of four months past that, or maybe four and a half months past that now. Where are you seeing those AI productivity benefits in your business?
Matt: I’ll come to that specifically in a moment. I think it is really important to understand about any new technology, and this has been seen over multiple cycles, that the technology discovery is important, but actually the vast majority of the value comes from the technology being diffused. There are lots of factors that make that harder or easier.
Our own experience, which I think is true for enterprises, is that new technology like AI—and we have been using machine learning for more than a decade—specifically generative AI, comes with complexity initially. There are a number of things that you need to adjust to, to be able to leverage the technology. That to me is primarily why, whilst the models might be improving at an exponential rate, if you looked at the absorption at an enterprise level and across the economy more broadly, I’d say that is linear at best—probably sublinear.
This is a very important focus area to get the benefits right. Specifically, where are we focused? Again, I think the benefits of AI need to be distributed. For us, that means we are using it in areas to protect our customers, most obviously in cyber and security. There has been a lot of focus on that in the last three or six months on a global basis, on scams and fraud. Secondly, we are using it to improve the customer service proposition. For us, that can be the companion app that we have rolled into our digital experience for our retail customers, and similarly for our business customers, so they can have revenue benefits.
More broadly, we are thinking about how we might alter the service proposition and how we might do things more efficiently. One of those areas is technology investment; we spend about $2.4 billion in terms of technology investment. For those same dollars year-on-year, we expect to be able to get substantially more. In our full-year results, we talked about achieving 60% more delivery over the last two years, and I think we can do more than that this year.
That generates capacity, and that generates value. The measurement and then the conversion of that is really important. From an investor perspective, it is often about: where do I see that in the P&L? What’s the net realised number? That is an important aspect. We need to think about where we are creating capacity in the organisation and what we are doing with that capacity. Are we realising it financially? Are we redirecting it somewhere else? Are we doing that consciously?
That is probably an area that we spent quite a bit of time on in the results, talking about exactly what we’d say about the benefits profile both this year and into the future. We are certainly growing in confidence about the benefits we have realised today and what we are going to see in 2027 and beyond.
Josh: Maybe the second-to-last question from me. You guys recently ranked fourth globally in the Evident AI Maturity Index. First of all, congratulations. But I guess that leaves me with confidence that you are well-placed to answer a longer-term question on the impact of AI on the workforce. If we are looking more like 10 years out, forgetting the short term of one, two, three, or five years, do you think that you guys will have more or less staff, or that the banking sector as a whole will have more or less staff? And what would they be doing?
Matt: How long out? 10 years?
Josh: 10 years.
Matt: 10 years is a long time, especially the second part of your question. Look, I think this is one of things that has probably been overstated in the near term because, like I said, new technology like AI creates new things that need to be done and additional complexity to really leverage it. There also will be changes to the way you lead, how you use the technology, changes to the way work is done, and the design of work.
On a like-for-like basis, I think you could say there’d be fewer people. The question is: how different will the business model look? There are certainly roles that exist today that didn’t exist in the past. There are areas that we are investing in that, until recently, we hadn’t been. But then there are also things that we should be able to do more simply than we have in the past.
If I went to a macro level, what I think is important from a national level, and then for us as a subset of that, is preparing and thinking about how work can change. We need to build additional skills and capability, making sure that everyone inside CBA, and more broadly, has a sense of agency. Creating anxiety and uncertainty for people without a way to actually build additional capability or skills is not particularly effective.
Secondly, at a national level, one of the dimensions we need to think about is: how is the value going to accrue to Australia and to Australians? That is true of a firm as well, which is: what are the capabilities? Going back to your question earlier around competitive advantage, where is the IP? What do you want to build and own yourself, and what do you want to rent or rely upon? What are the new industries, companies, and capabilities that need to be developed? At a national level, being a high-adoption country without being high in capability is not a great formula.
Similarly, from a company perspective: what are the new capabilities? And of course, look at what additional services we could provide for our customers, and how we can do that most effectively overall.
It has clearly been overstated, the impact on the labour market in the near term, but that is not to say that there won’t be changes. I don’t think they’ll be uniform, and they won’t happen over the same sort of compressed period. But I think for the vast majority of people that work within banking, some aspect of their role will change.
I remember talking to the head of LinkedIn earlier this year, and they noted that there are millions of roles on the LinkedIn platform where it is the same role name, but actually, the skills and the tasks underneath that role have changed. The message is: if you are not changing, your role most likely is changing over time.
Again, I don’t think unproductive anxiety in this area is helpful at all, but trying to, as an organisation and as an employer, build agency, build capability, and help people think about how to build optionality into their career paths with the skills they have today is a huge focus for us. Getting the workforce engaged in this transition is critical overall. If you have highly engaged employees who are motivated, they are going to do a very good job serving customers. I don’t imagine in any foreseeable timeframe that there won’t be important roles for humans to be doing within banking, including many aspects of how we service our customers.
Josh: Final question from me. According to the board, you are at least signed on until 2028. I have to ask, and it is something we try and ask all the CEOs we speak to: when you leave, what is the one thing you hope your successor doesn’t change?
Matt: It is a good question. I always like that Andy Grove quote: when you imagine that you’ve just been fired as a CEO and you walk back into the role, what is the first thing you’d change, as opposed to the last thing?
What I think would be valuable would be to make sure, whoever that is, we do a good job of sharing the context of what we tried to do, what we think worked, and what we were unable to do as well as we would have liked. For a company like CBA and big brands, you have high levels of expectation—people can call that a social licence, but I think it is more about trying to equip whoever is in my role, and also just senior leadership roles, with context. Context is super important and helps people make better decisions.
I hope they do a tremendous job because it is a great institution. I have been very lucky to be associated with it for such a long period of time, and I’m sure there will be many things that we won’t have gotten right during that time, and hopefully, they’ll get those things right.
Josh: Thank you for your time.
Matt: Pleasure.
This material has been prepared by Investors Mutual Limited (“IML”) AFSL 229988 and distributed by Natixis Investment Managers Australia Proprietary Limited, ABN 60 088 786 289, AFSL 246830. IML is the responsible entity and investment manager for the IML Funds.
Although Natixis Investment Managers Australia believes that this material is correct, no warranty of accuracy, reliability, or completeness is given, including for information provided by third parties except for liability under statute which cannot be excluded. This material is not personal advice. The material is for general information only and does not take into account your personal objectives, financial situation or needs. You should consider and consult with your professional advisor whether the information is suitable for your circumstances. The opinions expressed in the materials are those are the speakers and may not necessarily be those of Natixis Investment Managers Australia or its affiliate investment managers.
Any mention of specific company names, securities or asset classes is strictly for informational purposes only and should not be taken as a recommendation to buy, hold, or sell. The material may not be reproduced, distributed, or published in whole or in part without the prior written consent of IML or Natixis Investment Managers Australia.
Copyright 2026 Natixis investment Managers Australia. All rights reserved.
INVESTMENT INSIGHTS & PERFORMANCE UPDATES
Subscribe to receive IML’s regular performance updates, invitations to webinars as well as regular insights from IML’s investment team, featured in the Natixis Investment Managers Expert Collective newsletter.
IML marketing in Australia is distributed by Natixis Investment Managers, a related entity. Your subscriber details are being collected by Natixis Investment Managers Australia, on behalf of IML. Please refer to our Privacy Policy. Natixis Investment Managers Australia Pty Limited (ABN 60 088 786 289) (AFSL No. 246830) is authorised to provide financial services to wholesale clients and to provide only general financial product advice to retail clients.